Trump trade war: Global economy bleeding billions as tariffs escalate

President Trump’s latest tariffs on 60 nations and soaring oil prices are hammering global markets and manufacturing, with no end in sight.
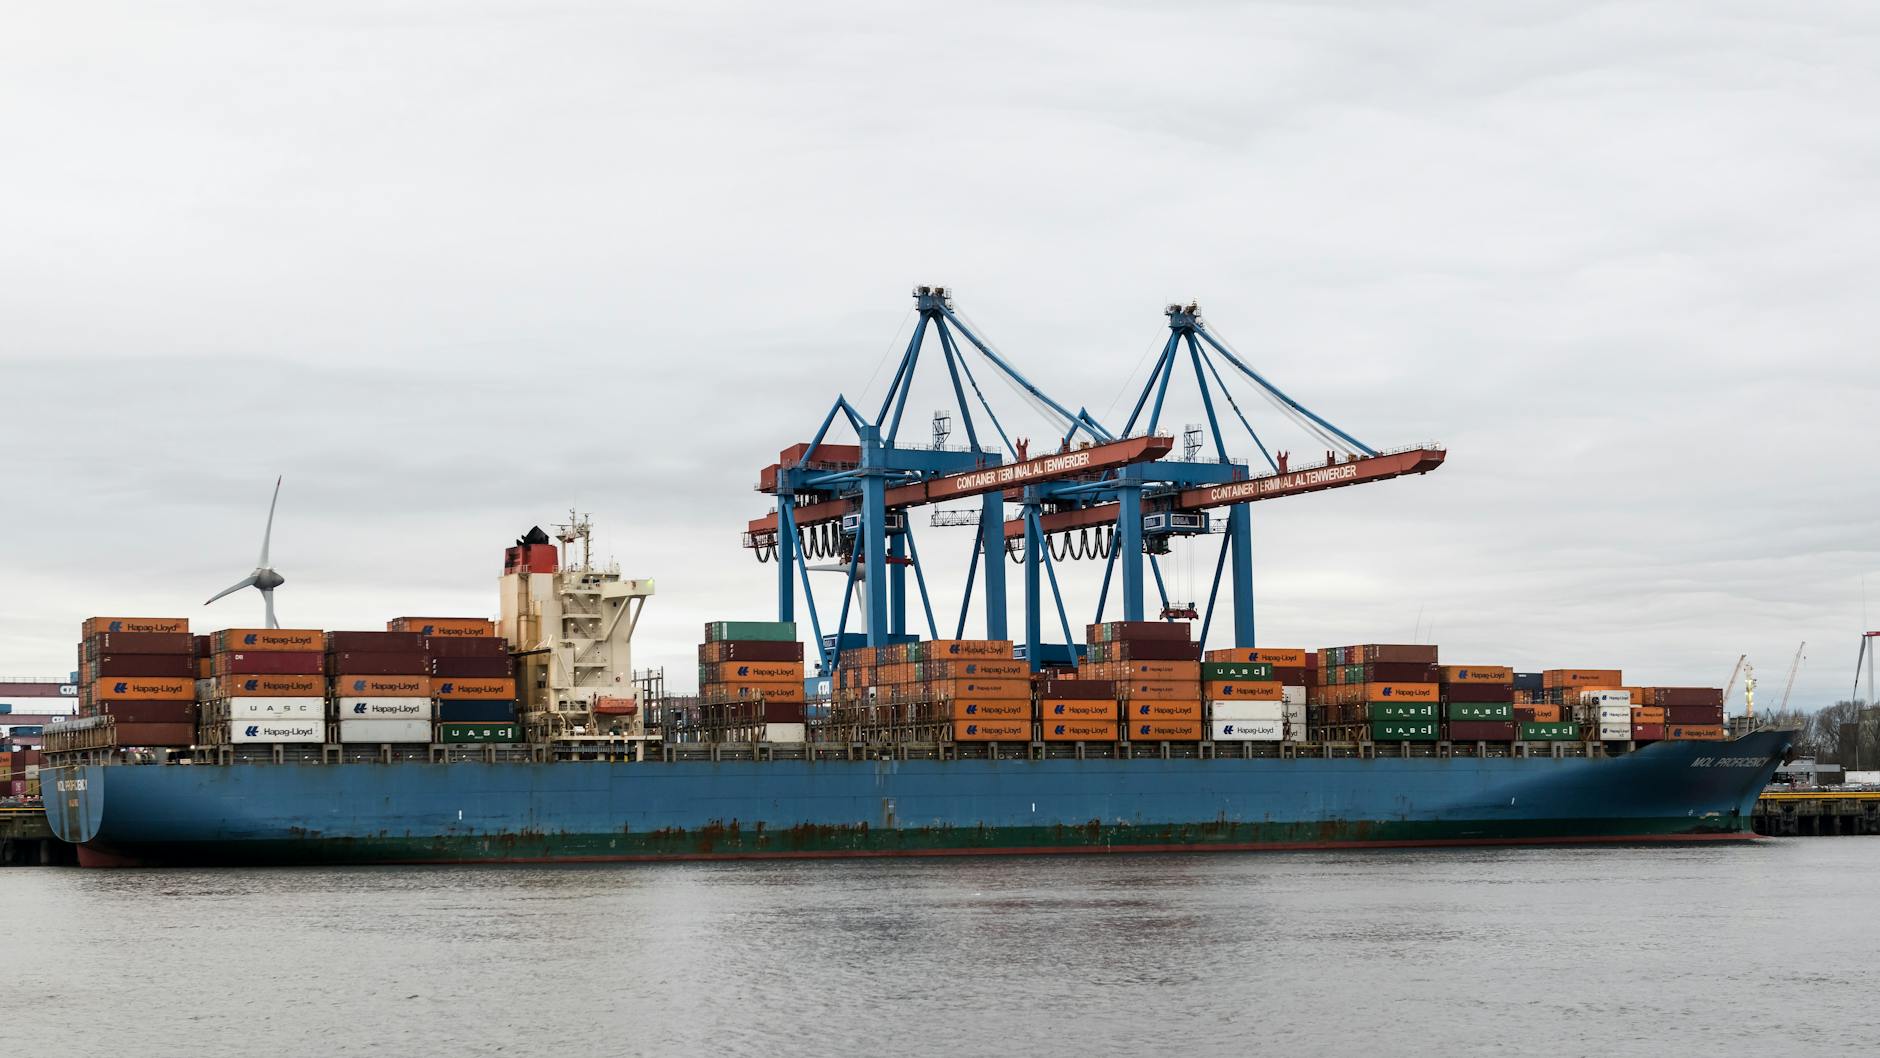
President Donald Trump’s trade war is exacting a mounting toll on the global economy, with new tariffs covering 99% of U.S. imports and oil prices surging past $100 a barrel. The combined shock has wiped more than $1 trillion from stock markets, undermined manufacturing, and heightened fears of a prolonged downturn. Economists warn the costs are being borne not just by American consumers, but by producers from Australia to India.
The latest tariff escalation
After the Supreme Court struck down his earlier 10% tariffs in February, Trump moved swiftly to impose a fresh round of levies. On Monday, he announced a 12.5% tariff on imports from 60 nations, covering virtually all goods entering the United States. The administration justified the move by accusing foreign competitors of using forced labor to undercut U.S. companies—a claim critics dismiss as a pretext. Ambassador Jamieson Greer, the U.S. trade representative, led a sham inquiry that produced no credible evidence, according to trade experts. The real rationale, as stated in the official announcement, was simply “in accordance with the specific direction of the President.”
Market turmoil and job losses
Financial markets recoiled. Bloomberg’s “Magnificent 7 Index,” which tracks Apple, Microsoft, Amazon, Nvidia, Meta, Tesla and Alphabet, plunged nearly 5% overnight—a loss of $797 billion in market value, or $1.1 trillion. The sell-off reflects investor unease over the massive spending on artificial intelligence that has buoyed both the U.S. and Australian economies. Meanwhile, Trump’s promise that tariffs would bring back manufacturing jobs has backfired. Since his “liberation day” tariff assault in April, roughly 100,000 factory jobs have disappeared, undercutting a core campaign pledge.
Global fallout and IMF warnings
The pain is spreading worldwide. The International Monetary Fund, which downgraded its global growth forecasts two weeks ago, identified four key risks: a re-escalation of war in the Middle East, exuberance in AI markets, rising tariffs, and failure to curb public spending. All four are now materializing. Oil prices at $100 a barrel are squeezing import-dependent nations, while the tariff war disrupts supply chains from Australian beef producers—exempted from the levies—to Indian rice farmers facing higher export costs. The IMF’s nightmare scenario is becoming reality, with the U.S. budget deficit widening further. Through the first nine months of the fiscal year, the deficit has ballooned, adding to global instability.
Carve-outs expose contradictions
Despite his rhetoric about protecting American consumers, Trump carved out exceptions for beef, coffee, jet fuel and certain petroleum blends—products that would pinch voters and industries dear to his base. The selective exclusions betray the policy’s true aim: leveraging tariffs as a political tool rather than a coherent economic strategy. The move also ignores the lesson of China’s tariff-for-tariff retaliation, which forced Trump to abandon his original “liberation day” plans. Analysts see the same miscalculation at play in the Middle East, where Trump underestimated Iran’s ability to close the Strait of Hormuz, driving up oil prices.

What lies ahead
With oil prices high, markets volatile, and manufacturing in retreat, the global economy faces a dangerous inflection point. Trump’s willingness to weaponize trade policy, combined with his administration’s unpredictable approach to geopolitics, leaves little room for stability. The IMF has warned that further escalation could tip the world into recession. For now, the cost of Trump’s trade war keeps rising—and no off-ramp is in sight.